Commercial Real Estate
Finance commercial real estate with MHV lending solutions for purchasing, refinancing, construction, and other property financing needs.
CRE, commercial mortgage
Loans from lenders who know the block.
Commercial real estate is where local knowledge earns its keep. Buy the building you rent. Refinance the one you own. Our lenders and underwriters know the difference between Kingston and White Plains.
Which property, which plan?
Owner-occupied commercial property
Buy or refinance the space your business operates from: retail, office, industrial, warehouse, restaurant, medical, mixed-use.
Investment property
Purchase or refinance income-producing commercial property held for rent.
Multifamily
Apartment buildings with 1- 4 units or more; purchase, refinance, or cash out to improve.
Construction
Ground-up and major renovation, including construction financing that converts to a permanent mortgage on residential property.
Refinance and cash-out
Lower your payment, pull equity to reinvest, or replace a balloon that's coming due.
We're financing our own neighborhood.
We know the market because we're in it. Rents, vacancy, absorption, what the assessor is doing, which towns move quickly on approvals. It shows up in how we structure a loan.
Structure built around the property, not a template. Term, amortization, and rate-reset periods matched to how you plan to hold the asset.
What lenders look at, in plain terms.
Commercial real estate lending comes down to a handful of measures. Here's what they mean, so nothing in the conversation is a surprise.
Loan-to-value (LTV)
How much of the property's appraised value we'll lend. The rest is your equity. Typical commercial LTVs are lower than residential mortgages; expect to bring meaningful equity.
Debt service coverage (DSCR)
Whether the property's net income comfortably covers the loan payment. A ratio above 1.25x means the property covers its payments with room to spare; lenders want a cushion. For owner-occupied property, we look at the business's cash flow instead.
Term and amortization
Commercial loans are commonly amortized over a long schedule, with a rate fixed for a set period, then reset or mature. We'll explain the structure and what happens at reset before you sign.
Guarantees
Owners with a meaningful stake typically personally guarantee the loan.
Third-party reports
An appraisal and, often, an environmental review are ordered by MHV and paid by the borrower. These take time; we'll provide a realistic timeline.
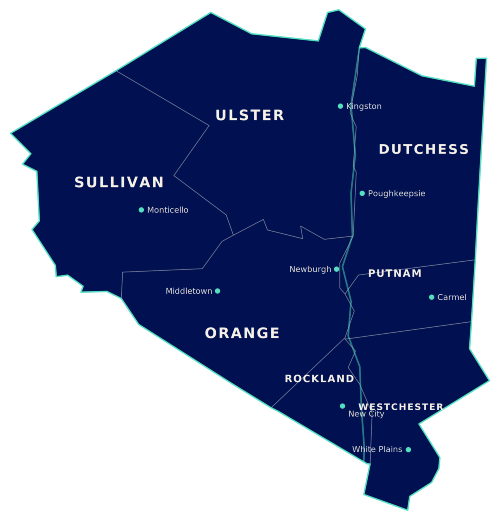
Where we lend.
We finance commercial property in the Hudson Valley: Ulster, Dutchess, Orange, Rockland, Sullivan, Putnam, and Westchester counties. The borrowing entity establishes MHV membership with a business savings account, which we can open alongside your application.
Your business lending experts
Tell us about the property.
A ten-minute call with a commercial lender will tell you whether the deal works and what it would take.
Frequently asked questions
Owner-occupied and investment commercial property, including retail, office, industrial, warehouse, mixed-use, and multi-family of five or more units, plus construction and renovation financing, throughout the Hudson Valley.
Commercial lenders finance a percentage of the appraised value and expect the borrower to bring the rest as equity; the exact percentage depends on the property type and how it's used.
Both. Talk to your lender for more details.
Longer than a business term loan, mainly because of the appraisal and any environmental review. Tell us your contract dates up front, and we'll build the calendar around them.
Yes. MHV's commercial lending team underwrites and decides in the Hudson Valley.
Our commercial lenders will guide you through the process, from an initial discussion about your goals, property, budget, and plan to how we would structure a loan. If you would like to move forward, we will put together a term sheet before you head to a full application and underwriting. Once approved, we'll send you a commitment letter to ensure a smooth closing.
What you need to bring depends on the type of loan you're requesting. Our commercial lending experts will walk you through this process. Though, you may need to bring with you:
-
Purchase contract or, for a refinance, current loan statements and payoff
-
Current rent roll and leases for income property
-
Two to three years of property operating statements (income and expenses)
-
Two to three years of business and personal tax returns for the borrowing entity and each guarantor
-
Personal financial statement for each guarantor
-
Entity documents: formation, operating agreement or bylaws, certificate of good standing
-
Schedule of real estate owned, with debt and income on each
-
For construction: plans, budget, contractor agreement, permits and approvals
Yes. SBA loan decisioning process is longer than MHV's internal business lending process. Equipment loan terms are up to 7 years, and Real Estate terms are up to 10 years. Talk to your lender for more details.
Disclosures: All loans are subject to credit approval, satisfactory appraisal, and membership eligibility. Rates, terms, and conditions are subject to change without notice. Personal guarantee required. Property insurance required; flood insurance required where applicable. Borrower is responsible for appraisal, environmental, title, and legal fees. Loans may include a balloon payment or rate adjustment; details provided in the commitment letter.